Modelo 347 is the annual informative declaration. You report every client and supplier with whom you had total transactions above €3,005.06 during the calendar year, including IVA. It is filed during February, covering the previous year, and no payment is attached. Its whole purpose is cross-checking: AEAT compares what you declare against what your clients and suppliers declare about you. A mismatch generates an automatic notice. This guide covers who must file, what counts towards the threshold, how to fill it in, and what to do when the numbers do not match.
Updated: July 2026
TL;DR
Who files: autónomos and companies with at least one client or supplier exceeding €3,005.06 in the calendar year
When: during February, covering the previous calendar year
Payment: none. It is purely informative.
Threshold: annual and cumulative, IVA included, not per invoice
Basis: accrual (devengo), meaning invoice date, not payment date
Penalty for not filing: €20 per omitted item, minimum €300, maximum €20,000
01. Who must file Modelo 347
You must file if you carry out a business or professional activity in Spain and had at least one counterparty exceeding €3,005.06 in the calendar year. This includes:
Autónomos in direct estimation (estimación directa)
Autónomos in módulos (objective estimation), who must also file if they meet the threshold
SLs and other companies
Community property entities (comunidades de bienes) and civil partnerships
You do NOT file if:
No single client or supplier reached €3,005.06 in the year
You are enrolled in the SII system (Suministro Inmediato de Información). SII businesses already report transaction data in real time, so Modelo 347 is redundant for them.
Your activity generated no transactions at all in the year
Being IVA-exempt does not exempt you from Modelo 347. A doctor or a regulated teacher who does not file Modelo 303 still files Modelo 347 if they exceeded the threshold with any client or supplier. For the full picture of which forms apply to you, see tax forms for autónomos in Spain.
02. What counts towards the €3,005.06 threshold
This is where most errors happen. The threshold has four characteristics that catch people out:
It is annual and cumulative, not per invoice. Four invoices of €800 to the same client total €3,200 and exceed the threshold. Many autónomos assume a single invoice must exceed the amount. It does not.
It includes IVA. The threshold is measured on the total invoice amount, IVA included, not on the taxable base. An invoice base of €2,600 plus 21% IVA comes to €3,146, which exceeds the threshold even though the base does not.
It applies separately to each counterparty. You assess each client and each supplier individually. There is no aggregation across different clients.
Sales and purchases are assessed separately. If you both sold to and bought from the same company, you evaluate each direction against the threshold on its own.
Transactions that do NOT go in Modelo 347:
Operations already reported in other informative declarations, particularly intra-community operations reported in Modelo 349
Operations subject to IRPF withholding that are already reported in Modelo 190. This is significant: if your client withheld IRPF from your invoices, those amounts are already declared through Modelo 190 and do not go in 347.
Imports and exports of goods
Transactions where you were not required to issue an invoice
The withholding exclusion means many autónomos who invoice exclusively Spanish businesses end up with nothing to declare in Modelo 347, because all their income is already reported through Modelo 190. The obligation typically bites when your clients are consumers, non-professional entities, or when you are reporting suppliers rather than clients.
03. Quarterly breakdown: how amounts are reported
Modelo 347 does not just ask for the annual total per counterparty. You break the amount down by quarter, reporting how much of the total corresponds to Q1, Q2, Q3, and Q4.
The allocation follows the accrual principle (devengo): an operation belongs to the quarter in which the invoice was issued, not the quarter in which it was paid. An invoice issued in December 2026 and paid in February 2027 goes in Q4 of the 2026 declaration.
This quarterly breakdown is the most common source of mismatches with the other party's declaration, because businesses sometimes record an invoice in the quarter they received it rather than the quarter it was issued.
04. How to file Modelo 347: step by step
Gather your annual data. Extract, for each client and supplier, the total invoiced or received during the calendar year with IVA included, broken down by quarter.
Filter by threshold. Keep only counterparties exceeding €3,005.06. Exclude anything already reported in Modelo 190 (IRPF withholding) or Modelo 349 (intra-community).
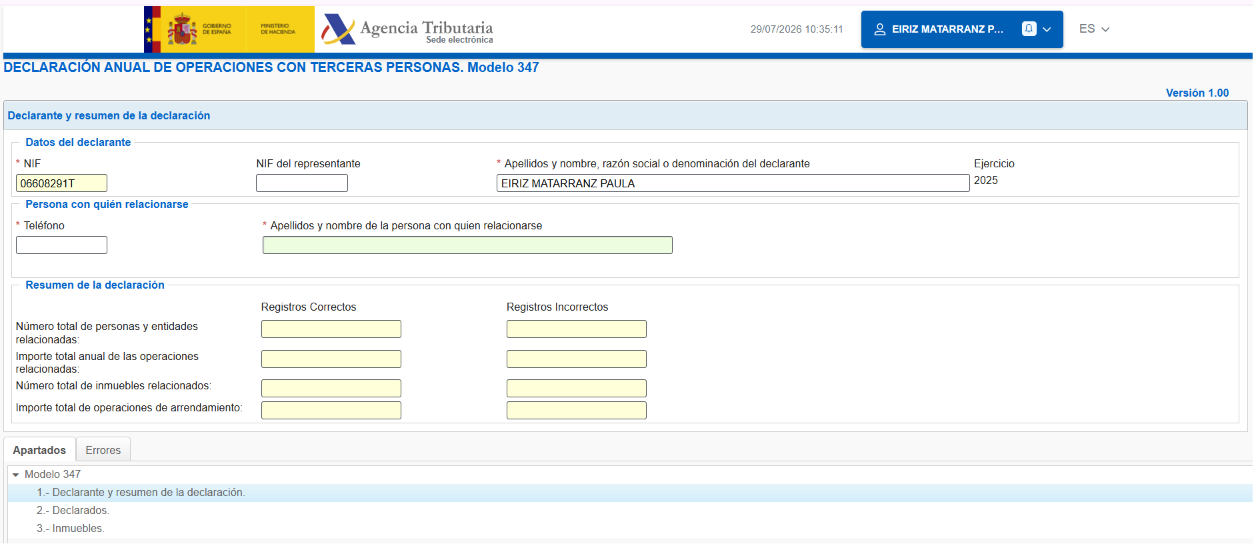
Access AEAT's Sede Electrónica. Go to sede.agenciatributaria.gob.es, search for "Modelo 347", and select "Presentación ejercicio [year]". You need a digital certificate or Cl@ve PIN. If you do not have one yet, see how to obtain a digital certificate for freelancers.
Fill in the identification section. Your NIF, name, and the financial year being declared.
Add each counterparty. For each one: NIF, name or company name, province code, the operation type (A for purchases, B for sales), the annual total, and the quarterly breakdown.
Check the totals. The sum of the quarterly amounts must equal the annual total for each counterparty. AEAT's form validates this before allowing submission.
Submit and save the receipt. You receive a submission receipt (justificante) with a secure verification code. Keep it.
05. Deadlines and penalties
Filing window: 1 to 28 February (or 29 in leap years), covering the previous calendar year. If the deadline falls on a weekend or holiday, it moves to the next working day.
Failure to file: €20 per omitted data item, with a minimum of €300 and a maximum of €20,000.
Incorrect or incomplete data: €150 to €300 depending on the type of error.
Late voluntary filing (before AEAT contacts you): the penalty is reduced significantly. File as soon as you notice the omission.
Because Modelo 347 carries no payment, the penalty is not proportional to any tax owed. It is a fixed infraction penalty for failing an information obligation.
06. What happens when your declaration does not match
AEAT reconciles every Modelo 347 against the declarations filed by your counterparties. If you declare €12,000 received from a client and that client declares €15,000 paid to you, both of you receive a notice (requerimiento) asking for clarification.
The most common causes of mismatch:
Timing differences. You issued an invoice on 28 December; your client recorded it in January. Both entries are defensible but they land in different quarters or even different years.
IVA included or excluded. One party declared the base, the other the total with IVA.
One party excluded withheld operations, the other did not. If your client withheld IRPF, those operations should not appear in 347 for either of you.
Credit notes not reflected. A corrective invoice (factura rectificativa) reduces the annual total. If only one party applied it, the totals diverge.
How to respond: reply to the requerimiento within the stated deadline with the invoice documentation supporting your figure. Most timing discrepancies are resolved with an explanation and copies of the invoices. Do not ignore the notice: an unanswered requerimiento can escalate into a fuller review.
Common mistakes with Modelo 347
Assuming the threshold is per invoice. It is annual and cumulative. Several small invoices to the same client can exceed it.
Measuring the threshold on the taxable base. It includes IVA. Use the total invoice amount.
Declaring operations already reported in Modelo 190. If your client withheld IRPF, those operations are excluded from 347. Declaring them creates a duplicate that triggers a mismatch.
Declaring intra-community operations. These belong in Modelo 349, not 347.
Allocating amounts by payment date. The criterion is the invoice date (accrual), not when the money arrived.
Forgetting suppliers. Modelo 347 covers both directions. Your gestor, your landlord, your software providers: if any exceeded €3,005.06, they go in.
Not filing because there is nothing to pay. It is informative, but mandatory. Not filing is an infraction regardless of the absence of payment.
Modelo 347: frequently asked questions
Do I file Modelo 347 if I only had one client all year?
It depends on two things: whether that client exceeded €3,005.06, and whether they withheld IRPF from your invoices. If they withheld IRPF, those operations are already reported in Modelo 190 and are excluded from 347. If they did not withhold (for example because they are a consumer or a non-professional entity) and the annual total exceeded the threshold, you file.
Does Modelo 347 include invoices I issued but have not been paid for?
Yes. The criterion is the accrual principle (devengo), based on the invoice date. An invoice issued in November 2026 and still unpaid in February 2027 belongs to the 2026 declaration.
What if I realise I made a mistake after filing?
File a corrective declaration. If you need to add data that was missing, file a complementaria. If you need to correct or remove data already submitted, file a sustitutiva, which replaces the original entirely. Doing this voluntarily before AEAT contacts you substantially reduces any penalty.
Do rental payments go in Modelo 347?
Business premises rent typically has IRPF withholding applied, which means it is reported in Modelo 180 and excluded from 347. If for any reason no withholding applied and the annual amount exceeded €3,005.06, it would go in 347.
Am I exempt from Modelo 347 if I am in módulos?
No. Autónomos in the objective estimation regime (módulos) file Modelo 347 under the same rules as everyone else if they exceed the threshold with any counterparty.
Do I file if my only counterparties are outside Spain?
EU business transactions go in Modelo 349, not 347. Non-EU transactions (exports of services) are generally excluded from 347 as well. If all your activity is with foreign clients, you likely have nothing to declare in 347, but check whether any Spanish suppliers exceeded the threshold.
Can my gestor file it for me?
Yes. Most gestorías file Modelo 347 as part of their annual service. What they need from you is complete, accurate bookkeeping: every invoice issued and received, correctly dated. The quality of the declaration depends entirely on the quality of the underlying records.