If you invoice a business in another EU country, you can issue the invoice without VAT under the reverse charge mechanism. But only if both you and your client are registered as intra-community operators and appear in the VIES database. Most autónomos discover this the hard way: they issue the invoice without VAT, the client refuses to pay it, or worse, AEAT reclassifies the sale as a domestic transaction and demands the 21% VAT from them. This guide covers how to register, how to verify your client, and what you file every quarter afterwards.
Updated: July 2026
Intra-community operations are transactions between businesses established in different EU member states. VAT on these transactions is not charged by the seller. Instead, the buyer self-assesses the VAT in their own country under the reverse charge mechanism (inversión del sujeto pasivo), declaring it as both input and output VAT. The net effect is zero cash movement for the tax.
The system exists to avoid businesses having to register for VAT in every country they trade with. But it only works if both parties are identifiable as VAT-registered businesses in their respective countries. That identification happens through the VIES database.
If either party is not in VIES, the transaction is not treated as intra-community. You must then charge Spanish VAT at 21%, exactly as if the client were in Spain.
The ROI (Registro de Operadores Intracomunitarios) is the Spanish register of businesses authorised to carry out intra-community transactions. Being registered as autónomo is not enough. You need a separate registration in the ROI.
How to register:
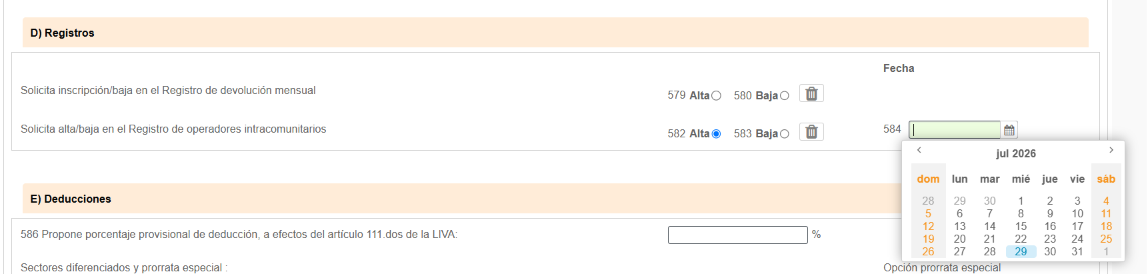
If AEAT rejects your application, the most common reasons are: no demonstrable business activity yet, tax debts outstanding, or inability to prove the intended EU transactions are real. You can reapply once the issue is resolved.
Before issuing any invoice without VAT, verify your client's VAT number in VIES (the EU VAT Information Exchange System). This is not optional diligence: it is your evidence if AEAT questions the transaction later.
How to verify:
If you enter your own number as requester, VIES issues a consultation number (número de consulta). This is the strongest evidence you can have: it proves you checked on a specific date and that the number was valid at that moment. Keep it with the invoice.
If the number comes back invalid, do not issue the invoice without VAT. Contact the client and ask them to confirm their registration status. Some countries have a delay between national VAT registration and appearing in VIES, so a client may be legitimately registered domestically but not yet visible in the EU system.
Once both parties are in VIES, the invoice to an EU business client differs from a domestic one in three ways:
Everything else stays the same: consecutive numbering, date, description, payment terms. For the full field-by-field invoice structure, see how to make an invoice in Spain and mandatory invoice details.
Every intra-community operation must be reported on Modelo 349, the recapitulative declaration. It is informative: no payment is attached.
AEAT cross-references Modelo 349 against VIES data submitted by other member states. If you declare €8,000 invoiced to a German company and that company declares €10,000 received from you, both tax authorities see the mismatch. Discrepancies generate a notice (requerimiento) asking for clarification.
The reverse charge works both ways. When you buy services from an EU supplier who invoices you without VAT (software subscriptions, advertising platforms, EU-based freelancers), you are the one who must self-assess the VAT.
In practice, on your Modelo 303 you declare the same amount as both output VAT (IVA repercutido) and input VAT (IVA soportado). The two cancel out, so you pay nothing extra, but the operation must appear in the return. Omitting it is a filing error even though the net tax is zero.
These purchases also go into Modelo 349, in the acquisitions section.
Important: you can only receive invoices without VAT from EU suppliers if you are in the ROI and your number is in VIES. If you are not registered, EU suppliers will charge you their own country's VAT, which you cannot recover through Modelo 303.
The legal maximum is three months from filing Modelo 036. In practice most approvals arrive in three to six weeks. Apply well before you expect to issue your first EU invoice, because registration does not apply retroactively.
No. Until your registration is approved and your number appears in VIES, you must charge Spanish VAT at 21%. If you invoice without VAT during the waiting period, AEAT can reclassify the transaction and claim the uncollected VAT from you.
You cannot apply the reverse charge. Charge Spanish VAT at 21%. Ask the client to register as an intra-community operator in their own country if they want future invoices without VAT. Some small businesses in other member states are not VAT-registered at all, in which case they are treated like consumers.
No. The ROI covers EU transactions only. Purchases from non-EU suppliers follow different rules: they are imports of services, and you also self-assess VAT on them in Modelo 303, but they do not go in Modelo 349 and do not require ROI registration.
Yes. AEAT can deregister you if you stop carrying out intra-community operations, if you fail to file Modelo 349 repeatedly, or if you have unresolved tax debts. If you are deregistered, your VIES entry disappears and clients can no longer apply the reverse charge to your invoices.
No. They are separate filings covering different things. Modelo 303 is your quarterly VAT return where you settle what you owe. Modelo 349 is an informative declaration of intra-community operations with no payment attached. If you have EU business clients, you file both.